Bank Statement Loans
Qualify using personal or business bank statements instead of tax returns — built for self-employed borrowers whose tax returns don't reflect their real cash flow.
Read MoreEntrust Home Lending helps buyers and investors across Cypress finance everything from a starter home near Towne Lake to a rental property off Fry Road, with programs ranging from FHA and conventional to DSCR and hard money for investors.
Cypress has grown fast over the last decade, and master-planned communities like Bridgeland and Towne Lake bring their own HOA and appraisal quirks that out-of-town lenders often miss. Entrust Home Lending is headquartered right off Cypresswood Drive, in the middle of the area it covers — close enough to know which builders’ preferred lenders to watch for and how a new-build contract differs from a resale purchase agreement.
New construction is a bigger share of the market in Cypress than in most of Harris County, which changes the financing conversation: builder incentives tied to using their in-house lender, appraisal gaps on homes that haven’t been built yet, and rate-lock timing against a construction schedule that can slip. FHA and conventional financing both work here, and down payment assistance through TSAHC or SETHFC can apply to new construction the same way it does to resale, provided the paperwork is filed correctly and on time.
Cypress is also home to a growing number of self-employed buyers and small business owners for whom a standard W-2 underwriting file doesn’t reflect real income — bank-statement and non-QM programs exist specifically for that situation. And for the investors buying rental property off Fry Road or further out toward Waller County, DSCR financing qualifies the loan off the property’s rental income rather than personal income, with hard money available for a fix-and-flip or a deal that needs to close fast.
Cypress is an unincorporated part of Harris County, inside Houston’s extraterritorial jurisdiction rather than its city limits, so there’s no city property tax. Most subdivisions get water, sewer, and drainage through a municipal utility district (MUD) instead, and the MUD’s tax is part of the property taxes you’ll budget for; Bridgeland and Towne Lake, for example, each sit inside several MUDs. Texas requires the seller to give you a written notice about the MUD before you sign a binding contract. Homes are appraised by the Harris Central Appraisal District (HCAD), where you file your homestead exemption once the home is your principal residence.
Cy-Fair ISD serves most of Cypress, but not all of it. In Bridgeland, the Lakeland and Parkland villages are in Cy-Fair ISD, while Prairieland and Creekland are mostly in Waller ISD, with the southern part of Prairieland in Katy ISD. Confirm the district for the exact address.
Cypress Creek rises in Waller County and runs east through the area on its way to Spring Creek. During Hurricane Harvey in 2017 it reached record levels, and thousands of homes in its watershed flooded. The Harris County Flood Control District builds regional detention basins along Little Cypress Creek ahead of new development. Check any address on FEMA’s Flood Map Service Center and on the Flood Control District’s Flood Education Mapping Tool.
Bridgeland, a Howard Hughes community begun in 2006, is still adding homes in its Creekland village, and Towne Lake is built around a 300-acre lake. One thing buyers of brand-new homes miss: a never-occupied new home doesn’t come with the Texas seller’s disclosure, which is where resale buyers learn about floodplains and past flooding. Check the flood maps yourself before you sign.
Towne Lake, Bridgeland, Fairfield, Coles Crossing, Blackhorse Ranch, Cypress Creek Lakes, and the surrounding area.
Loan Programs
A sample of what we originate — see the full list of loan programs for everything we offer.
Qualify using personal or business bank statements instead of tax returns — built for self-employed borrowers whose tax returns don't reflect their real cash flow.
Read MoreFinancing not backed by a government agency — usually means fewer overlays, more flexible property types, and no upfront mortgage insurance premium for buyers with stronger credit.
Read MoreGrant and bond programs that can cover part or all of your down payment and closing costs, often paired with FHA or conventional financing.
Read MoreQualify investment property financing off the property's rental income, not your personal income — no tax returns or employment verification required.
Read MoreGovernment-backed financing built for buyers with limited down payment savings or a credit history that doesn't fit a conventional box — including flexible credit-score guidelines and 100% financing programs.
Read MoreHome financing for borrowers who file taxes with an ITIN rather than a Social Security number.
Read MoreAward-Recognized Loan Officers
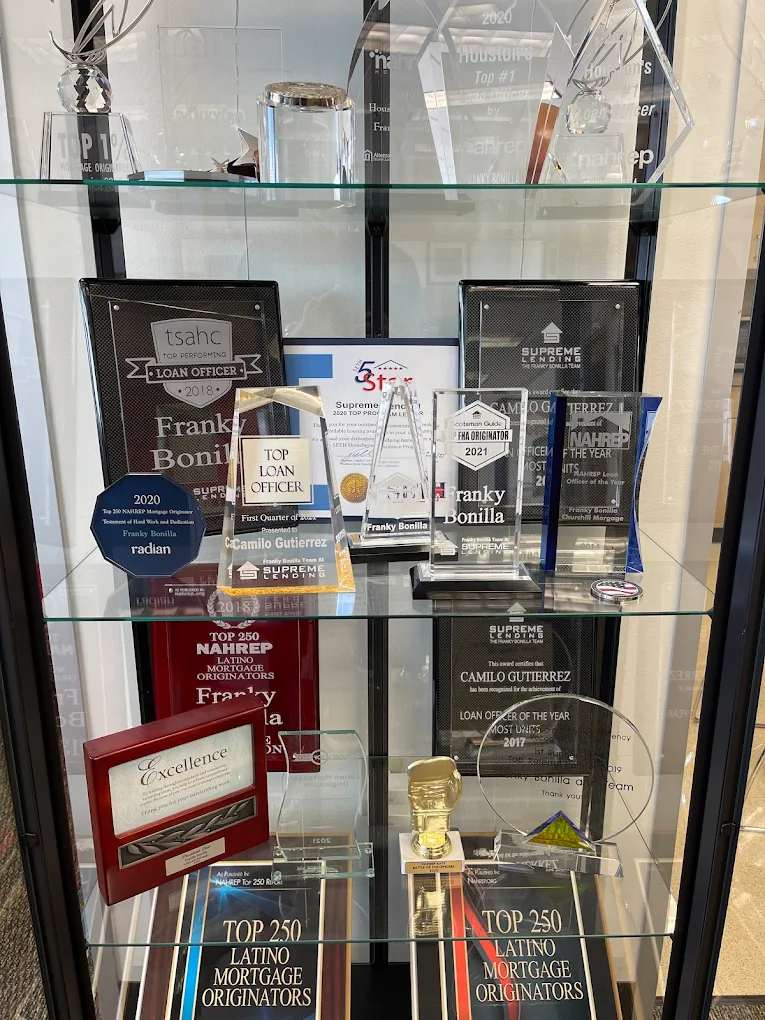
NAHREP Top 250
Latino Mortgage Originators
TDHCA Top Performing
Loan Officer
Scotsman Guide
Top FHA Originator
NAHREP Loan Officer
of the Year
How It Works
01
See what your dream home could look like. Run the numbers yourself with our calculators — no commitment, no credit pull, just a starting point.
Try the Calculators →02
You've got a rough idea what you can afford — now it's time to connect with a loan officer who can guide you through the next steps.
Meet Our Team →03
A loan officer reviews your file personally and tells you what you qualify for, and what to fix if you don't yet.
04
We handle documentation, appraisal, and underwriting in-house and keep you updated at every step.
05
Clear to close, sign, and get your keys — with milestone updates the whole way.
Cy-Fair ISD serves most of Cypress. Some newer areas differ: in Bridgeland, the Lakeland and Parkland villages are Cy-Fair ISD, while Prairieland and Creekland are mostly Waller ISD and southern Prairieland is Katy ISD. Always check the district for the specific address.
A municipal utility district (MUD) is a local government district that builds and runs water, sewer, and drainage for a development, paid for with bonds that are repaid through its own property tax. Most Cypress subdivisions are in one. The seller must give you a written MUD notice before you sign a binding contract, and the MUD tax belongs in your monthly budget alongside county and school taxes.
No. In Texas, a new home that has never been lived in is exempt from the seller's disclosure, which is where resale buyers learn whether a home is in a floodplain or has flooded. For new construction, look the address up on FEMA's Flood Map Service Center and the Harris County Flood Control District's mapping tool before you sign.
Talk to a local loan officer who already knows the market.
or call (346) 730-1153 or (832) 953-9171
Entrust AI can make mistakes and cannot quote rates or approve loans. For anything specific, talk to a loan officer.
Common questions