Bank Statement Loans
Qualify using personal or business bank statements instead of tax returns — built for self-employed borrowers whose tax returns don't reflect their real cash flow.
Read MoreEntrust Home Lending works with buyers and investors throughout Tomball, from first-time homebuyers to DSCR and hard money financing for investors building a rental portfolio.
Tomball still has some of the small-town feel that’s disappeared from parts of Harris County, alongside newer master-planned communities like Northpointe, Rock Creek, and Woodtrace. That mix means two very different buyer profiles show up in the same zip code: longtime residents refinancing or buying near downtown Tomball, and newer families moving into a subdivision built in the last few years — each with different appraisal comparables to work from.
FHA financing covers a large share of first-time purchases here, and TSAHC or SETHFC down payment assistance can reduce the cash needed to close when a buyer qualifies. Tomball also has a sizable population of self-employed business owners and independent contractors tied to the surrounding industrial and energy-sector employers — for those files, bank-statement and non-QM underwriting qualify income off actual cash flow instead of a tax return that understates it.
For investors, Tomball’s newer developments and older in-town lots both come up in DSCR and hard money conversations — DSCR for a stabilized rental qualified off its own rent, and hard money for a purchase or renovation that needs to close faster than conventional underwriting allows.
Tomball is an incorporated city, but many homes described as being in Tomball sit outside its limits, in unincorporated Harris County or across the line in Montgomery County. That changes which taxes apply and who appraises the home: the Harris Central Appraisal District (HCAD) for Harris County addresses, and the Montgomery Central Appraisal District for homes like those in Woodtrace, in Pinehurst. Many subdivisions in the area, including Wildwood at Northpointe, are also in a municipal utility district (MUD) with its own property tax, and the seller must give you a written MUD notice before you sign a binding contract.
Tomball ISD covers about 83 square miles of northwest Harris and southwest Montgomery counties: the city itself plus areas such as Northpointe, Rose Hill, and Creekside Park in The Woodlands. Some nearby addresses fall in Klein ISD or Cy-Fair ISD instead.
Willow Creek drains about half of the city on its way to Spring Creek. During Hurricane Harvey in 2017, about 30 inches of rain fell on Tomball and Willow Creek rose above its 100-year level, though the city’s damage was small compared with much of the Houston area. Check the address on FEMA’s Flood Map Service Center before you sign, and remember that a brand-new, never-occupied home doesn’t come with the Texas seller’s disclosure that asks about past flooding.
Newer communities in Tomball ISD include Wildwood at Northpointe, which has Tomball Memorial High School inside it, and Oakhill Reserve, where Toll Brothers and Tri Pointe are selling new homes in 2026. Down payment assistance through TSAHC can be used on new construction as well as resale homes, subject to income and purchase-price limits.
Northpointe, Rock Creek, Lakes of Rosehill, Woodtrace, Copperfield, and the surrounding area.
Loan Programs
A sample of what we originate — see the full list of loan programs for everything we offer.
Qualify using personal or business bank statements instead of tax returns — built for self-employed borrowers whose tax returns don't reflect their real cash flow.
Read MoreFinancing not backed by a government agency — usually means fewer overlays, more flexible property types, and no upfront mortgage insurance premium for buyers with stronger credit.
Read MoreGrant and bond programs that can cover part or all of your down payment and closing costs, often paired with FHA or conventional financing.
Read MoreQualify investment property financing off the property's rental income, not your personal income — no tax returns or employment verification required.
Read MoreGovernment-backed financing built for buyers with limited down payment savings or a credit history that doesn't fit a conventional box — including flexible credit-score guidelines and 100% financing programs.
Read MoreHome financing for borrowers who file taxes with an ITIN rather than a Social Security number.
Read MoreAward-Recognized Loan Officers
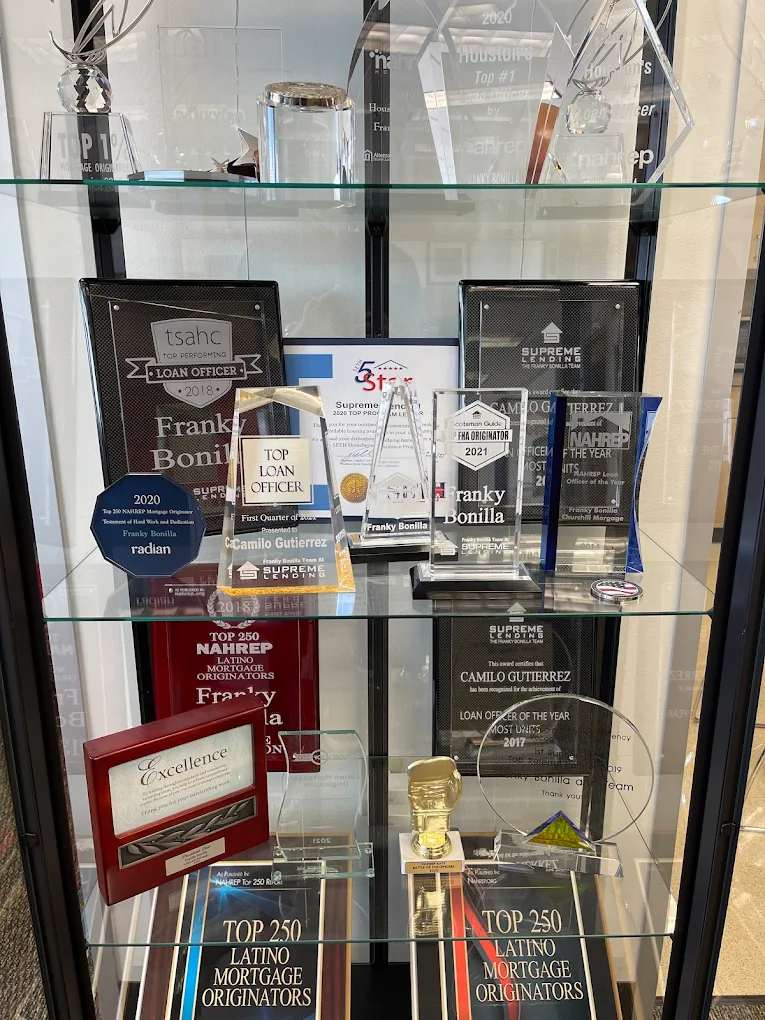
NAHREP Top 250
Latino Mortgage Originators
TDHCA Top Performing
Loan Officer
Scotsman Guide
Top FHA Originator
NAHREP Loan Officer
of the Year
How It Works
01
See what your dream home could look like. Run the numbers yourself with our calculators — no commitment, no credit pull, just a starting point.
Try the Calculators →02
You've got a rough idea what you can afford — now it's time to connect with a loan officer who can guide you through the next steps.
Meet Our Team →03
A loan officer reviews your file personally and tells you what you qualify for, and what to fix if you don't yet.
04
We handle documentation, appraisal, and underwriting in-house and keep you updated at every step.
05
Clear to close, sign, and get your keys — with milestone updates the whole way.
Not necessarily. Tomball is an incorporated city, but many homes described as being in Tomball are in unincorporated Harris County or in Montgomery County. That affects which taxes apply and which appraisal district values the home, so check the property's taxing units on the appraisal district's website before you buy.
Tomball ISD serves the city and surrounding areas of northwest Harris and southwest Montgomery counties, including Northpointe, Rose Hill, and Creekside Park. Some nearby addresses are in Klein ISD or Cy-Fair ISD, so check the specific address.
Once you own the home and live in it as your principal residence, file with your county's appraisal district: HCAD for Harris County or the Montgomery Central Appraisal District. The usual deadline is April 30. If the previous owner already had the exemption for the year you buy, yours generally starts the next January; on a new home with no exemption that year, you may be able to claim it for the rest of the year you buy.
Talk to a local loan officer who already knows the market.
or call (346) 730-1153 or (832) 953-9171
Entrust AI can make mistakes and cannot quote rates or approve loans. For anything specific, talk to a loan officer.
Common questions