Bank Statement Loans
Qualify using personal or business bank statements instead of tax returns — built for self-employed borrowers whose tax returns don't reflect their real cash flow.
Read MoreEntrust Home Lending is headquartered in Houston and lends across Texas from here — FHA, ITIN, and bank-statement financing for buyers who don't fit a conventional box, plus DSCR and hard money for investors, with a bilingual team for Spanish-speaking borrowers.
Houston’s housing market moves differently block to block — a starter home in Cypress, a rebuild lot near the Heights, a rental portfolio play in Humble. Entrust Home Lending is headquartered off Cypresswood Drive in northwest Houston, but the license behind it is a Texas mortgage company license, not a Houston-only one — the same team underwrites files for buyers and investors anywhere in the state, with Houston as the home base and the deepest local knowledge.
That local knowledge shows up most on files that don’t fit a standard box. Houston is one of the largest Hispanic and Latino metro populations in the country, and a meaningful share of buyers here are more comfortable working in Spanish through the whole process — pre-qualification, document collection, and closing — not just a translated brochure. It’s also a market with a large self-employed and gig-income population, where bank-statement and non-QM underwriting matter as much as FHA does for first-time buyers.
Harris County itself adds a layer most out-of-area lenders don’t bother learning: appraisal timelines and comparable-sales patterns vary significantly between neighborhoods like Cypress, the Heights, and Humble, and down payment assistance eligibility often depends on which side of a county or school-district line a property falls on. Two state and regional programs come up often for Houston-area buyers — see below — alongside DSCR and hard money financing for investors building a rental portfolio across the metro.
Most of Houston is in Harris County, where the Harris Central Appraisal District (HCAD) sets property values; small parts of the city reach into Fort Bend and Montgomery counties, which have their own appraisal districts. Once the home is your principal residence, you can file for a homestead exemption with HCAD. The application is free, so there’s no need to pay a company to file it for you. Many subdivisions just outside the city limits get water and sewer from a municipal utility district (MUD), which adds its own property tax, so count it when you compare homes.
The City of Houston has no zoning code. What can be built next door is often governed instead by a neighborhood’s deed restrictions, so read them before you sign.
Houston sits on a network of bayous, and flood risk can change from one street to the next. If a home is in a FEMA Special Flood Hazard Area and the loan is FHA, VA, USDA, or a conventional loan sold to Fannie Mae or Freddie Mac, flood insurance is required. Check the address on FEMA’s Flood Map Service Center and on the Harris County Flood Control District’s Flood Education Mapping Tool, and read the seller’s disclosure, which in Texas asks whether the home is in a floodplain and whether it has flooded before. During Hurricane Harvey in 2017, homes inside the Addicks and Barker reservoir pools on the west side flooded and stayed underwater as the Army Corps of Engineers released water down Buffalo Bayou.
Houston ISD covers most of the city, but parts of Houston are served by Aldine, Alief, Cy-Fair, Fort Bend, Katy, Klein, and Spring Branch ISDs. Check the district for the exact address, not the city name.
For income-eligible buyers purchasing inside Houston city limits, the City of Houston’s Homebuyer Assistance Program offers a forgivable loan toward the down payment and closing costs. It requires homebuyer education and a participating lender, and its funding and rules change, so check the Housing and Community Development Department’s current guidelines before you count on it.
Cypress, Spring, Tomball, The Woodlands, Klein, Humble, Katy, Champions, and the surrounding area.
Loan Programs
A sample of what we originate — see the full list of loan programs for everything we offer.
Qualify using personal or business bank statements instead of tax returns — built for self-employed borrowers whose tax returns don't reflect their real cash flow.
Read MoreFinancing not backed by a government agency — usually means fewer overlays, more flexible property types, and no upfront mortgage insurance premium for buyers with stronger credit.
Read MoreGrant and bond programs that can cover part or all of your down payment and closing costs, often paired with FHA or conventional financing.
Read MoreQualify investment property financing off the property's rental income, not your personal income — no tax returns or employment verification required.
Read MoreGovernment-backed financing built for buyers with limited down payment savings or a credit history that doesn't fit a conventional box — including flexible credit-score guidelines and 100% financing programs.
Read MoreHome financing for borrowers who file taxes with an ITIN rather than a Social Security number.
Read MoreAward-Recognized Loan Officers
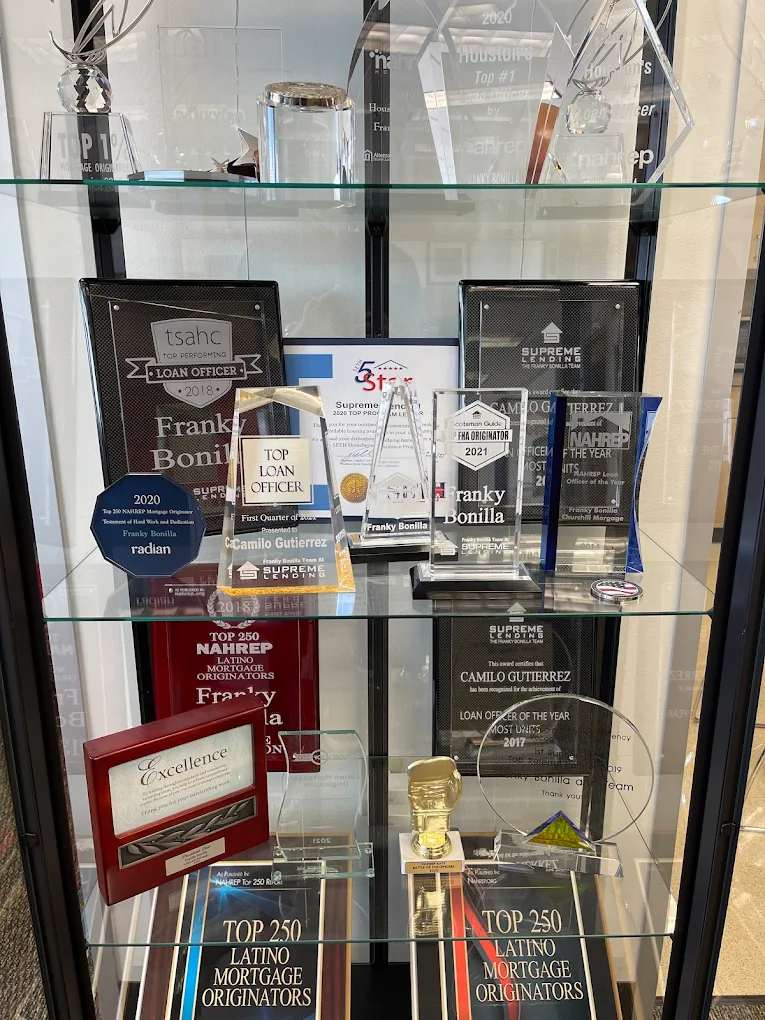
NAHREP Top 250
Latino Mortgage Originators
TDHCA Top Performing
Loan Officer
Scotsman Guide
Top FHA Originator
NAHREP Loan Officer
of the Year
How It Works
01
See what your dream home could look like. Run the numbers yourself with our calculators — no commitment, no credit pull, just a starting point.
Try the Calculators →02
You've got a rough idea what you can afford — now it's time to connect with a loan officer who can guide you through the next steps.
Meet Our Team →03
A loan officer reviews your file personally and tells you what you qualify for, and what to fix if you don't yet.
04
We handle documentation, appraisal, and underwriting in-house and keep you updated at every step.
05
Clear to close, sign, and get your keys — with milestone updates the whole way.
Entrust Home Lending's office is at 9720 Cypresswood Dr, Suite 180, Houston, TX 77070, in northwest Harris County near SH 249. Office hours are Monday through Friday, 8:00 am to 6:00 pm, with Saturday and Sunday by appointment.
No. The City of Houston has no zoning code, so many neighborhoods rely on deed restrictions to control what can be built. Read the deed restrictions for any home you're considering before you sign a contract.
It's required if the home is in a FEMA Special Flood Hazard Area and the loan is FHA, VA, USDA, or a conventional loan sold to Fannie Mae or Freddie Mac. Outside those zones it's optional, but worth pricing. If you need it, buy it before closing: a flood policy bought in connection with a new mortgage doesn't have the usual 30-day waiting period.
The City of Houston's Homebuyer Assistance Program offers a forgivable loan to income-eligible buyers purchasing inside city limits, with homebuyer education and a participating lender required. Statewide programs from TSAHC and SETHFC are also available across the Houston area. Funding and rules change, so check each program's current guidelines.
Talk to a local loan officer who already knows the market.
or call (346) 730-1153 or (832) 953-9171
Entrust AI can make mistakes and cannot quote rates or approve loans. For anything specific, talk to a loan officer.
Common questions