Bank Statement Loans
Qualify using personal or business bank statements instead of tax returns — built for self-employed borrowers whose tax returns don't reflect their real cash flow.
Read MoreEntrust Home Lending works with buyers and investors across the Klein area on FHA, conventional, DSCR, and hard money financing.
Klein sits between Spring and Cypress and shares a lot of the same fast growth — new construction in Gleannloch Farms alongside established neighborhoods like Klein Forest and Lakewood Forest, and buyers ranging from first-time purchasers to seasoned investors.
FHA financing with a low down payment and flexible credit guidelines covers most first-time purchases in the area, often stacked with TSAHC or SETHFC down payment assistance to bring closing costs down further. Klein’s mix of long-established and newly built subdivisions also means appraisal comparables can differ meaningfully within the same few miles — worth having a loan officer who pulls the right comps rather than the first ones a system suggests.
Klein has a sizable number of self-employed buyers and small business owners, particularly in and around Spring Creek Oaks, for whom bank-statement or non-QM underwriting fits better than a conventional file built around a W-2. And for investors, DSCR and hard money financing both apply here the same way they do across the rest of Harris County — DSCR qualifying off a rental property’s own income, hard money for a purchase or renovation that needs to move on a tighter timeline.
Klein is unincorporated and has had no post office of its own since 1906, so homes here carry Houston, Spring, or Tomball mailing addresses. The area is roughly bounded by SH 99 to the north, SH 249 to the west, and I-45 to the east, and in practice it’s defined by Klein ISD, a district formed in 1938 that covers about 88 square miles. Because the mailing address doesn’t tell you the school district, confirm it for the exact property. Entrust’s own office on Cypresswood Drive is in ZIP code 77070, which is split between Klein ISD and Cy-Fair ISD.
Homes in Klein are in Harris County and are appraised by the Harris Central Appraisal District (HCAD), where filing a homestead exemption is free once the home is your principal residence. There’s no city property tax in unincorporated Klein, but many subdivisions are in a municipal utility district (MUD) with its own tax; Gleannloch Farms, a master-planned community on a former Arabian horse farm, is in Harris County MUD 367. The seller must give you a written MUD notice before you sign a binding contract.
Cypress Creek runs through the middle of the Klein area, and Klein ISD’s southern boundary follows it for a long stretch. Hurricane Harvey brought record flooding to the Cypress Creek watershed in 2017. Check any address on FEMA’s Flood Map Service Center and on the Harris County Flood Control District’s Flood Education Mapping Tool, and read the seller’s disclosure, which asks whether the home has flooded before.
Gleannloch Farms, Spring Creek Oaks, Klein Forest, Lakewood Forest, and the surrounding area.
Loan Programs
A sample of what we originate — see the full list of loan programs for everything we offer.
Qualify using personal or business bank statements instead of tax returns — built for self-employed borrowers whose tax returns don't reflect their real cash flow.
Read MoreFinancing not backed by a government agency — usually means fewer overlays, more flexible property types, and no upfront mortgage insurance premium for buyers with stronger credit.
Read MoreGrant and bond programs that can cover part or all of your down payment and closing costs, often paired with FHA or conventional financing.
Read MoreQualify investment property financing off the property's rental income, not your personal income — no tax returns or employment verification required.
Read MoreGovernment-backed financing built for buyers with limited down payment savings or a credit history that doesn't fit a conventional box — including flexible credit-score guidelines and 100% financing programs.
Read MoreHome financing for borrowers who file taxes with an ITIN rather than a Social Security number.
Read MoreAward-Recognized Loan Officers
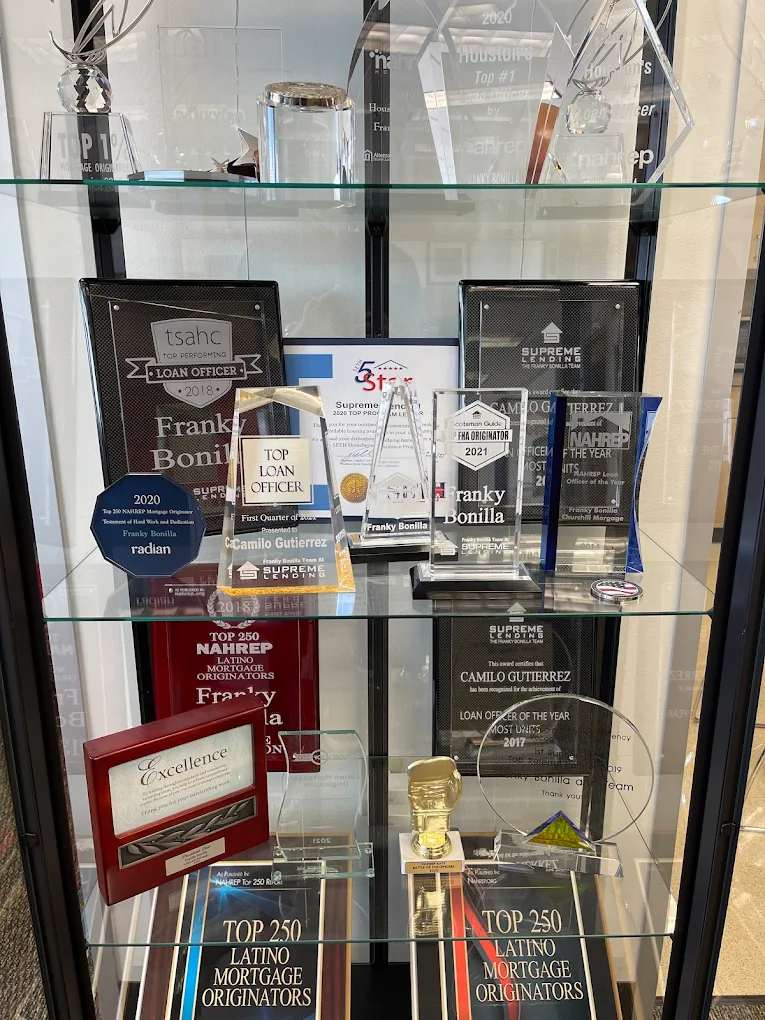
NAHREP Top 250
Latino Mortgage Originators
TDHCA Top Performing
Loan Officer
Scotsman Guide
Top FHA Originator
NAHREP Loan Officer
of the Year
How It Works
01
See what your dream home could look like. Run the numbers yourself with our calculators — no commitment, no credit pull, just a starting point.
Try the Calculators →02
You've got a rough idea what you can afford — now it's time to connect with a loan officer who can guide you through the next steps.
Meet Our Team →03
A loan officer reviews your file personally and tells you what you qualify for, and what to fix if you don't yet.
04
We handle documentation, appraisal, and underwriting in-house and keep you updated at every step.
05
Clear to close, sign, and get your keys — with milestone updates the whole way.
Klein has had no post office of its own since 1906, so mailing addresses use neighboring cities. The area is defined mostly by Klein ISD, so check the school district and county on the property record rather than going by the city in the address.
Many are. Klein is unincorporated, so water, sewer, and drainage in many subdivisions come from a municipal utility district that levies its own property tax; Gleannloch Farms, for example, is in Harris County MUD 367. The seller must give you a written MUD notice before you sign a binding contract.
It's required if the home is in a FEMA Special Flood Hazard Area and the loan is FHA, VA, USDA, or a conventional loan sold to Fannie Mae or Freddie Mac. Cypress Creek runs through the Klein area and reached record levels during Hurricane Harvey, so check the flood map for any address. If you need a policy, buy it before closing: flood coverage bought with a new mortgage doesn't carry the usual 30-day wait.
Talk to a local loan officer who already knows the market.
or call (346) 730-1153 or (832) 953-9171
Entrust AI can make mistakes and cannot quote rates or approve loans. For anything specific, talk to a loan officer.
Common questions