Bank Statement Loans
Qualify using personal or business bank statements instead of tax returns — built for self-employed borrowers whose tax returns don't reflect their real cash flow.
Read MoreEntrust Home Lending works with buyers and investors throughout the Katy area, which spans three counties, on FHA, conventional, DSCR, and hard money financing.
Katy is unusual in that the same town spans Harris, Fort Bend, and Waller counties, which means property tax rates, appraisal district timelines, and even flood-zone mapping can differ block to block — sometimes within the same school district and the same subdivision. Knowing which county a given address in Cinco Ranch or Cross Creek Ranch falls into, and what that means for taxes and closing, is worth catching before underwriting rather than during it.
Katy’s growth has been driven heavily by relocation — families and professionals moving from out of state or from company transfers — which means a wide range of income documentation shows up in a typical file: straight W-2 income, employer relocation packages, and self-employed or 1099 income from buyers who moved their business with them. Conventional and FHA financing cover most owner-occupant purchases, with TSAHC down payment assistance available for qualifying buyers, while bank-statement and non-QM programs fit borrowers whose income doesn’t reduce cleanly to a W-2.
For investors, DSCR and hard money financing apply the same way they do elsewhere in the Houston area — DSCR qualifying a rental purchase off the property’s own income, and hard money covering a purchase or renovation that needs to close on a tighter timeline than conventional underwriting allows.
The City of Katy has land in Harris, Fort Bend, and Waller counties, and many homes with a Katy address, including those in Cinco Ranch and Grand Lakes, are outside city limits altogether. The county a home is in decides who appraises it: the Harris Central Appraisal District (HCAD), the Fort Bend Central Appraisal District (FBCAD), or the Waller County Appraisal District. That’s also where you file your homestead exemption once the home is your principal residence.
Most master-planned communities in the Katy area are in a municipal utility district (MUD), which pays for water, sewer, and drainage through its own property tax; Cinco Ranch alone is served by 11 of them. Texas requires the seller to give you a written MUD notice before you sign a binding contract, and the MUD tax belongs in your monthly budget.
Katy ISD covers about 181 square miles across all three counties, but not every Katy-area address is in it. The west side of Cross Creek Ranch, Jordan Ranch, and parts of Tamarron are in Lamar CISD, and parts of Waller County, including part of Sunterra, are in Royal ISD.
Buffalo Bayou begins near Katy, and the federal Addicks and Barker reservoirs were built in the 1940s to reduce flooding along it. During Hurricane Harvey in 2017, water held behind the reservoirs backed up onto private property upstream, flooding homes in parts of neighborhoods including Cinco Ranch and Grand Lakes. The Texas seller’s disclosure asks whether a home is in a flood pool or reservoir, and FEMA’s Flood Map Service Center shows mapped flood zones for any address.
Sunterra, in Waller County, and Tamarron, which has a Fulshear address, were among the Houston area’s busiest communities for new-home sales in 2025, and Elyson opened new sections in 2026. In Cross Creek Ranch, the last new homes have sold, and building has moved next door to Cross Creek West.
Cinco Ranch, Cross Creek Ranch, Grand Lakes, Falcon Ranch, Katy Lakes, and the surrounding area.
Loan Programs
A sample of what we originate — see the full list of loan programs for everything we offer.
Qualify using personal or business bank statements instead of tax returns — built for self-employed borrowers whose tax returns don't reflect their real cash flow.
Read MoreFinancing not backed by a government agency — usually means fewer overlays, more flexible property types, and no upfront mortgage insurance premium for buyers with stronger credit.
Read MoreGrant and bond programs that can cover part or all of your down payment and closing costs, often paired with FHA or conventional financing.
Read MoreQualify investment property financing off the property's rental income, not your personal income — no tax returns or employment verification required.
Read MoreGovernment-backed financing built for buyers with limited down payment savings or a credit history that doesn't fit a conventional box — including flexible credit-score guidelines and 100% financing programs.
Read MoreHome financing for borrowers who file taxes with an ITIN rather than a Social Security number.
Read MoreAward-Recognized Loan Officers
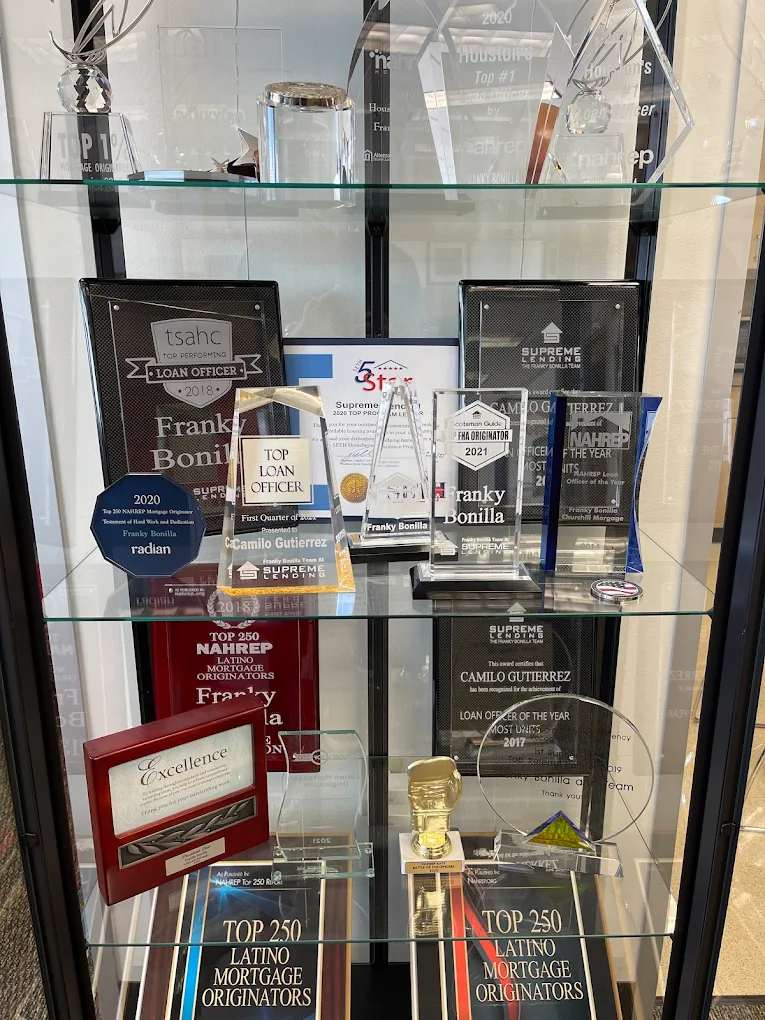
NAHREP Top 250
Latino Mortgage Originators
TDHCA Top Performing
Loan Officer
Scotsman Guide
Top FHA Originator
NAHREP Loan Officer
of the Year
How It Works
01
See what your dream home could look like. Run the numbers yourself with our calculators — no commitment, no credit pull, just a starting point.
Try the Calculators →02
You've got a rough idea what you can afford — now it's time to connect with a loan officer who can guide you through the next steps.
Meet Our Team →03
A loan officer reviews your file personally and tells you what you qualify for, and what to fix if you don't yet.
04
We handle documentation, appraisal, and underwriting in-house and keep you updated at every step.
05
Clear to close, sign, and get your keys — with milestone updates the whole way.
It depends on the county the home is in. Katy spans Harris, Fort Bend, and Waller counties, so the appraisal district is HCAD, FBCAD, or the Waller County Appraisal District. Many homes with a Katy address, including those in Cinco Ranch and Grand Lakes, are also outside Katy city limits.
No. Katy ISD covers most of the area, but the west side of Cross Creek Ranch, Jordan Ranch, and parts of Tamarron are in Lamar CISD, and parts of Waller County, including part of Sunterra, are in Royal ISD. Check the district for the specific address.
Yes. In 2017, water held behind the federal Addicks and Barker reservoirs backed up onto private property upstream, flooding homes in parts of neighborhoods including Cinco Ranch and Grand Lakes. When buying in the Katy area, check FEMA's flood maps and read the seller's disclosure, which asks whether the home is in a flood pool or reservoir and whether it has flooded.
Most master-planned communities in the Katy area are. A MUD pays for water, sewer, and drainage through its own property tax, and Cinco Ranch alone is served by 11 of them. The seller must give you a written MUD notice before you sign a binding contract.
Talk to a local loan officer who already knows the market.
or call (346) 730-1153 or (832) 953-9171
Entrust AI can make mistakes and cannot quote rates or approve loans. For anything specific, talk to a loan officer.
Common questions